Partner-managed
Cross River partner-managed solution
Cross River's partner-managed model gives partners maximum input into the card program.
- Partners use their own card processor and handle everything from ledgering to transaction approvals. They manage the entire customer experience while the bank performs program oversight.
- Card Management: Partners handle card creation, activation, suspension, closure, and replacement using their processor systems within the bank-approved construct.
How it works
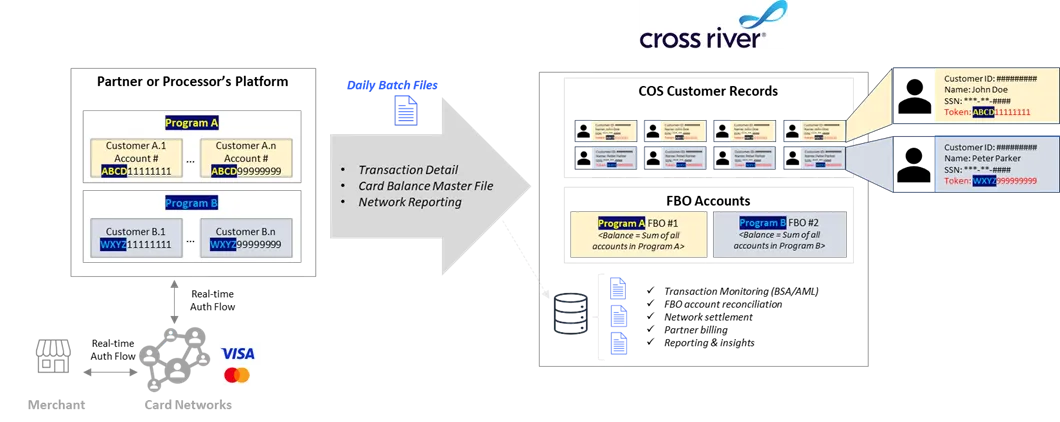
You or your processor are the system of record for all balances and authorizations. Cross River does not participate in the authorization flow.
For prepaid and debit card programs, Cross River holds all card funds in an FBO account with subledgers for each individual external account the partner's ledger holds. There are no individual DDA accounts per cardholder. Each customer (personal or business) must have a Customer ID, created by registering each in COS. This supports bank-required customer oversight.
What we offer
Cross River acts as the issuing bank, provides BIN sponsorship, network settlement, banking oversight, regulatory compliance oversight, and guidance on best practices.
This model lets partners tailor card programs while benefiting from Cross River's compliance oversight and expertise.
Cross River’s role
As the issuing bank, Cross River provides:
- BIN sponsorship: As a Principal member, Cross River sponsors the use of its Bank Identification Numbers (BINs), enables partners to offer cards without needing direct membership with Visa® or Mastercard®. Cross River allocated its assigned BINs to partner card programs.
- Oversight: Cross River ensures that card programs comply with Visa, Mastercard, and federal and state banking regulations from initial program evaluation and through ongoing oversight. Cross River monitors programs through a combination of daily and monthly file exchanges between the Partner and Cross River as well as regular audits of the Partner’s compliance to agreed upon policies and procedures.
- Network settlement and reporting: Cross River manages network settlement with Visa and Mastercard and reports card portfolio activity to the same card networks on a quarterly basis as required by network rules.
Partner’s role
The partner is responsible for:
- Processor relationship and integration: Partners select and manage the card processor. The processor connects directly to the card networks (Visa, Mastercard) on behalf of the issuing BINs Cross River assigns. Partners then manage the ongoing operational relationship with the processor and customer experience flows, while exchanging information with Cross River to support settlement and compliance oversight.
- Ledger management: Partners maintain a ledger of customer balances and transaction history, aligned with Cross River’s compliance requirements.
- Transaction authorization: Partners manage real-time transaction approvals through the card processor, applying program-defined business rules, fraud controls, and transaction limits. Cross River works with partners to ensure these rules are compliant with network standards and regulatory expectations.
- Card network connectivity: Partners are responsible for establishing and managing connectivity between their processor and the card network (Visa, Mastercard). This includes receiving authorization requests, submitting clearing files, and handling chargebacks. Partners also manage disputes.
- Card lifecycle management: Partners manage card creation, activation, suspension, closure, and replacement flows through the card processor systems, with Cross River providing guidance to maintain best practices and compliance. Refer to partner-managed for more details.
- Credit card application decisioning: Specifically for credit card programs where Cross River is the lender of record. Partners are required validate, submit, and supplement credit card application data using Cross River's PreApproval V2 API.
Balance visibility and FDIC insurance
When Cross River holds customer funds in an FBO account, federal banking regulations require that partners must make beneficial owner identity and ownership interests ascertainable for FDIC pass-through insurance. Partners achieve this through one of three partner-managed models, depending on where partners hold funds and maintain the program ledger.
The three partner-managed variations are:
- Card only BIN sponsorship: Cross River does not hold customer funds
- FBO subledger model: Cross River's preferred model. Cross River holds funds in partner FBO account with subledgers; partner maintains program ledger on their end, but updates individual customer balances in COS at the FBO account subledger level on a regular basis (at least once daily).
- FBO pooled account model: Cross River can also hold funds in a partner FBO account; partner maintains the program ledger and provides information about individual customer balances to Cross River via daily balance files.
Refer to Balance and ledger models for details on selecting the right structure for your program.