Loan process
Loan origination process
Loan origination process overview
Cross River's proprietary Lending platform consists of several interconnected modules to faciliate efficinet and compliant loan origination:
- Oversight: For housing policies and rules.
- Preapproval: For real time application data validation via pav2 (Cross River’s patent pending application validation software).
- Origination: For issuing loans via Arix (Cross River’s proprietary origination software).
- Manual Review: For resolving exceptions detected by, Cross River rules engine, MPLLifeCycle.
- Funding: For disbursing funds to borrowers via Arix.
- Selling: For allocating loans to varying financing sources.
- Contracts: For viweing system configurations such as financing sources and fees.
- Hooks: For listening to webhook events and keeping track of the loan through its life cycle.
For a typical loan, the entire origination process takes around 10 seconds from origination to funding plus another 5 minutes for the initial seasoning to kick off.
1. A Market Place Lending partner (“MPL”) submits a loan application for preapproval
The application is submitted regardless of its approval status. If the status changes, the MPL can resubmit to provide its latest decision. This process aligns with Fair Lending laws, ensuring all applications are reviewed uniformly.
The MPL submits a loan application to the Preapproval v2 API to provide the bank with its final decision for each application.
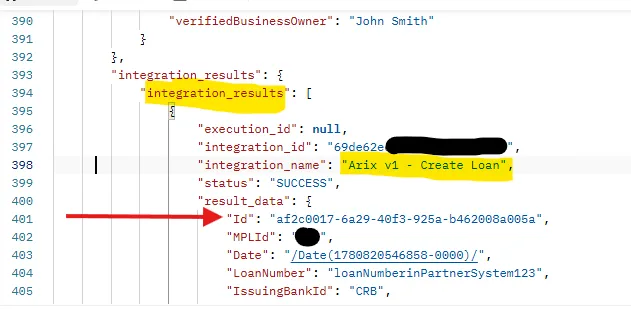
When "Create Arix Loan" integration in Preapproval v2 is enabled, the system will pass the application data into Arix when approved and ready to fund, and you may skip step 2.
The Arix unique GUID will be returned in the response and needs to be saved, as in step 2.
2. MPL submits loan payload (a loan tape) to Arix
Upon MPL approval of the loan application and decision to originate and fund, the MPL sends the complete loan payload to Arix using the POST /Loan API call including:
- Borrower Type: Consumer and business loans
- Loan Type: Secured and unsecured loans
- Loan Structure: Term loans or revolving lines of credit
This step initiates the loan creation process within Arix. Arix assigns a unique GUID to the loan and sets its initial status to Received.
3. MPL uploads required loan documents
The MPL uploads all necessary loan documents to Arix using thePOST /Loan/{id}/Attachments API call.
Arix automatically confirms all required documents (Loan agreement, Credit Report, etc.) were submitted. Once all required documents are received, the loan status updates to Docs Complete.
4. MPLLifeCycle performs compliance checks
MPLLifeCycle automatically conducts compliance checks based on predefined rules housed in Oversight.
This step is where Cross River ensures the loan details are complete and accurate
If the loan passes all compliance rules, the status updates to Passed Compliance. If any rule fails, the status changes to Compliance Failed, and detailed reasons are provided via a Hooks event. The MPL must address these issues before proceeding. The MPL uses the Manual Review UI or API module to communicate with Cross River teams, upload additional documents or correct the loan details.
5. MPLLifeCycle approves the loan
After successful compliance checks, the loan status updates to Approved indicating readiness for funding.
6. Arix initiates loan funding
The loan status changes to InFunding during this process. Arix supports various funding rails, including ACH, Same-Day ACH, RTP®, FedNow®, RPPS, Check, Internal Transfer, Wire and Push to Card. The platform allows setting fallback options if a chosen rail fails. Once funds are successfully sent and received, the loan status updates to Funded. Arix manages the full lifecycle of Funding, including rejects, returns, pulling funds back and cancellations.
7. Selling kicks off loan seasoning period
After funding, the loan enters an initial seasoning period prior to being allocated to the appropriate financing channel.
8. Loan sale or retention decision
Post initial-seasoning (typically 3 business days), your loans are allocated to temporary or permanent financing arrangements (provided by external parties or Cross River) as established with you.
9. Servicing data submission and reconciliation
MPL submits daily servicing data until the loan is paid off/closed. This is used to monitor loans originated by Cross River.