Advanced authorization flow
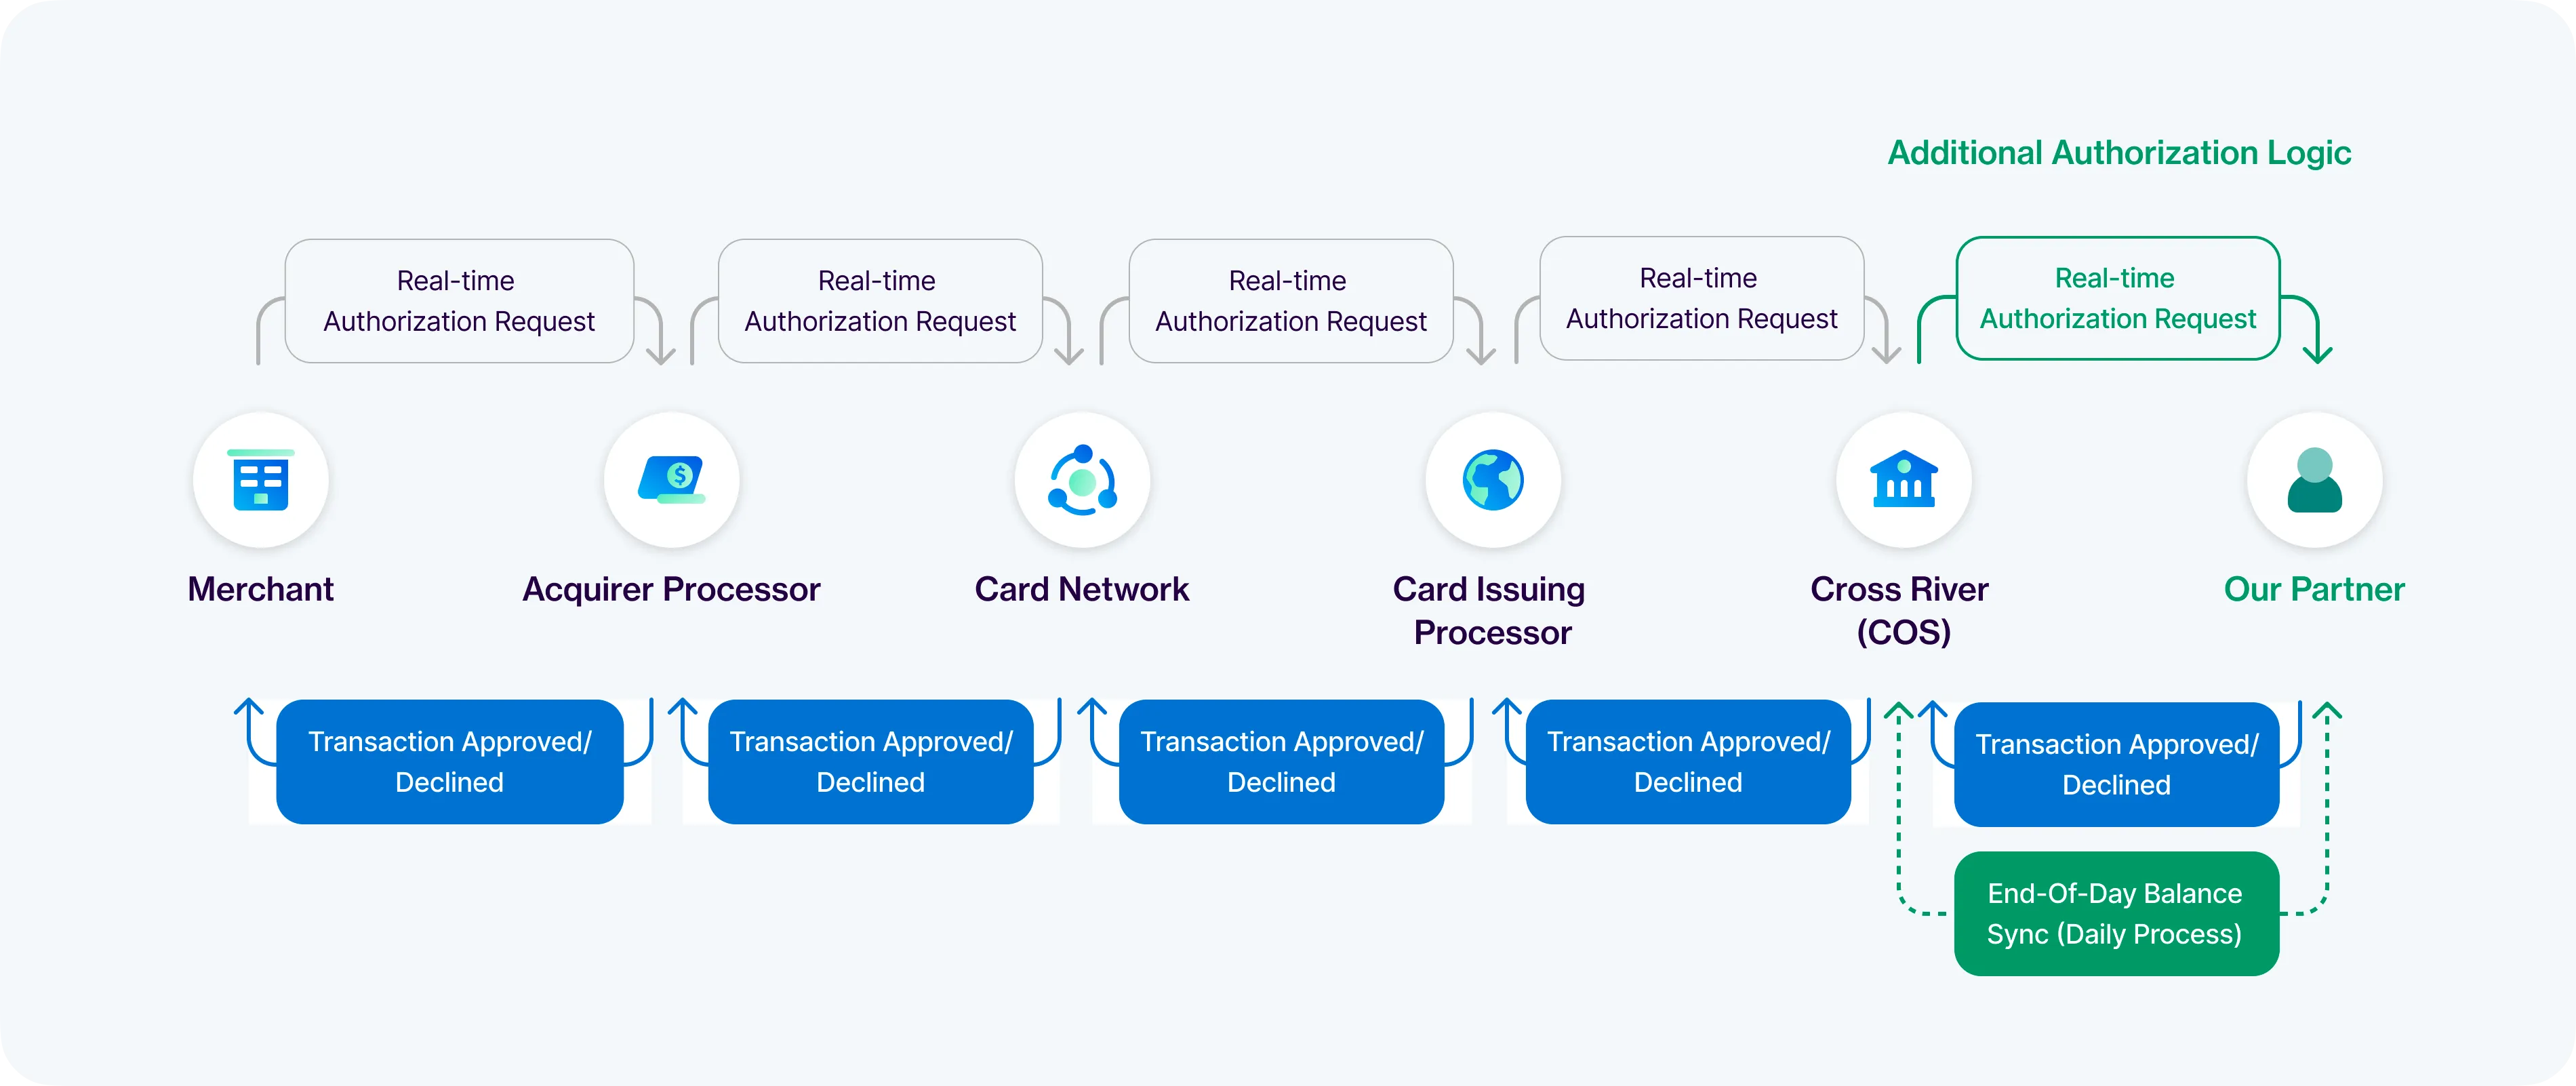
- The cardholder taps, swipes, or enters card info at the merchant’s terminal or app using a Cross River card from a partner who has been certified for Advanced Authorization.
- The merchant sends transaction data to its acquirer processor.
- The acquirer processor formats the request and requests authorization from Cross River via the appropriate card network (Visa, Mastercard).
- The card network forwards the transaction request to the issuer processor associated with the BIN on the card for real time authorization.
- The transaction request is received by Cross River, who in turn reaches out to the partner to request an authorization.
- For Direct mode this occurs with every transaction.
- Authorizing transactions.
- For Direct mode the partner holds the balance and will authorize each transaction based on the cardholder’s balance and potentially other business rules (account standing, fraud, withdrawal limits, etc.).
- The card issuer or issuing processor responds with an approval or decline decision to the card network.
- The card network routes the decision back to the acquirer processor.
- The merchant receives the response — and the transaction is approved or declined at the point of sale.
- At the end of each day, the partner reconciles their daily operation and updates account records in Cross River. This includes:
- Receiving a reconciliation file from Cross River to ensure all transactions were received and processed correctly.
- Updating any accounts at Cross River to ensure the balances are kept up to date with the partner's ledger.